
Común: Your money, your way
- Rating
- 4.8
- Downloads
- 500.00K
- Content Rating
- Everyone
Común: Your money, your way - Screenshots
Pros
- Clear overview of spending
- balances
- and recent transactions
- Useful tools for organizing money around personal financial goals
- Modern interface makes everyday account management feel approachable
- Convenient access to essential banking features from a mobile device
- Helpful notifications can make it easier to track account activity
Cons
- Some features may depend on your country
- account type
- or eligibility
- Identity verification can feel lengthy during initial setup
- Limited functionality may be available without an active Común account
- Mobile banking access depends on a stable internet connection
- Support response times may vary during busy periods
Común: Your money, your way - Description
- App Name
- Común: Your money, your way
- Package Name
- app.comun.mobile
- Developer
- Comun
- Category
- Finance
- Last Updated
- Aug 30, 2022
- Version
- 2.29.0
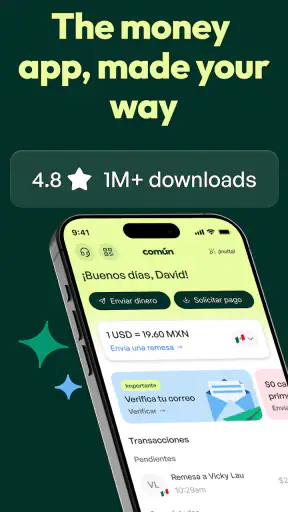
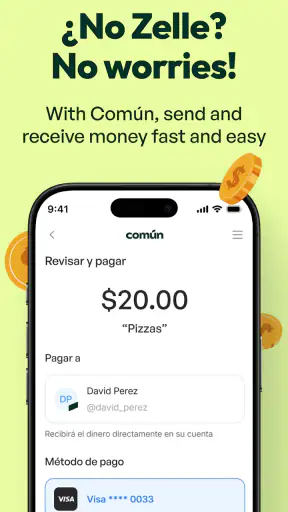
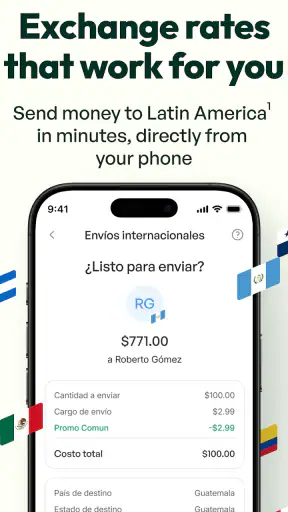
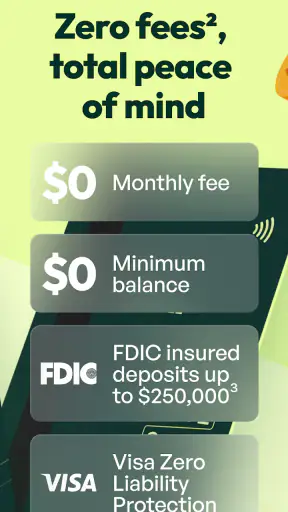
I approached Común as a money app that wants to become part of everyday life rather than a tool you open only during tax season or a financial emergency. Developed by Comun, it combines person-to-person payments, transfers to Latin America, and access to a Visa debit card in one place. That combination gives it an immediate practical appeal, especially for people who regularly move money between the United States and Latin American countries.
My first impression was that the app’s value depends less on novelty and more on whether its central jobs match your routine. If you need to pay someone, send money abroad, or use a debit card without juggling several unrelated services, the idea is easy to understand. If your finances are already organized around a bank, a dedicated remittance service, and a separate card, Común has a higher bar to clear.
It is a free finance app for everyone, and its current release is version 2.29.0. The application has built a strong public reception, with a 4.8 average from roughly twenty-two thousand ratings and more than half a million installs. Those figures do not replace personal testing, but they do suggest that the basic experience has resonated with a substantial group of users.
What Común feels like during the first week
The first week is where the app makes its best case. A financial product becomes easier to appreciate when it removes small points of friction, and Común’s appeal comes from bringing several familiar money tasks into one destination. Instead of thinking, “Which service should I use for this transfer?” you can start with a single app designed around payments and cross-border use.
That is particularly useful in a realistic household scenario. Imagine being paid in the United States while supporting relatives in Latin America. You may need to send money on a schedule, pay a friend who covered a shared expense, and use a card for ordinary purchases. Común is relevant because those activities belong to the same financial routine, even though traditional alternatives often separate them into different apps and accounts.
The Visa debit card also changes how I think about the service. A remittance-only product is useful at the moment money is sent, but a debit card can give the app a continuing role in daily spending. That matters for habit formation: an app is more likely to stay installed when it is connected to something you use regularly instead of a single occasional transaction.
Still, I would not treat the first week as proof that Común should replace every financial service you have. Setting up a new money app takes attention, and the real question is whether the payment and transfer workflow is noticeably simpler for you. If you rarely send money to Latin America and already have a dependable debit card, the added convenience may be too modest to justify changing your routine.
Where the cross-border focus makes a difference
Común is more specific than a general budgeting app or a standard digital wallet. Its identity is tied to sending money to Latin America, so the strongest use case is not simply “I need another way to pay.” It is “I need a practical bridge between my everyday money and people or expenses connected to Latin America.” That distinction helps set realistic expectations.
For occasional users, I would begin with a small, ordinary transfer rather than immediately reorganizing a large part of my finances. This gives you a chance to understand the steps, timing, recipient experience, and any verification prompts without making the first test unnecessarily stressful. It is also a sensible way to see whether the app fits the countries and people you actually deal with.
One useful habit is to keep the purpose of each transfer clear before opening the app. Decide whether you are paying a person, supporting family, or moving money for your own use. That simple preparation makes it easier to notice whether Común is genuinely reducing effort or merely offering another interface for a task you already handle comfortably elsewhere.
The card is useful only if it becomes part of your routine
A Visa debit card sounds appealing, but the lasting value depends on how naturally it fits your spending. I would consider using it for a defined slice of my routine rather than treating it as an automatic replacement for my primary bank card. For example, it could be the card connected to money I intentionally set aside for everyday purchases or for expenses related to a cross-border household.
This approach creates a clearer test. After several weeks, you can ask whether the card makes payments easier, whether you remember to use it, and whether the app gives you a reason to check in beyond the initial setup. If you keep reaching for another card because it is already embedded in your wallet, Común may remain useful mainly for transfers.
The important trade-off is concentration versus flexibility. Having payments, transfers, and a debit card together is convenient, but it also means you may depend more heavily on one service. I prefer to keep an alternative payment method available, especially when traveling or handling an important payment. That is not a criticism unique to Común; it is simply good financial housekeeping when one app begins to occupy several roles.
Why the value can hold up month after month
Común earns lasting space when it becomes a reliable part of a repeated workflow. The strongest recurring pattern is a user who sends money to Latin America regularly and also wants a Visa debit card for local spending. In that situation, the app is not competing only on a single transfer. It is reducing the number of places you need to remember and the number of separate routines you need to maintain.
I also see value for people who coordinate family finances across borders. A person may not need advanced financial planning features; they may simply want a straightforward way to pay someone, send support, and access spending money. Común’s focus is easier to understand in that context than for someone looking for detailed investing tools, complex budgeting, or a full banking replacement.
The app’s free price lowers the cost of trying it, which is important for a service whose usefulness varies so much by personal circumstances. You can evaluate the workflow before deciding whether it deserves a permanent place on your phone. However, free access should not encourage careless use. Before sending meaningful amounts, I would still review every confirmation screen and make sure the recipient details are correct.
Another practical tip is to separate experimentation from dependence. During the first few recurring cycles, keep your existing method available until Común has proven itself in your actual schedule. This is especially sensible if a transfer supports rent, food, school, or another essential expense. A new app can be promising and still require a learning period before it becomes your only option.
Who will get the most recurring value
I think Común is best suited to people with a clear connection to its core use cases. That includes users who send money to Latin America, people who frequently pay others digitally, and anyone who wants a Visa debit card connected to the same financial environment. It may also appeal to someone who prefers a focused app over a traditional bank interface filled with features they never use.
The fit is weaker for a user whose main goal is detailed budgeting. Común’s central promise is movement and access to money, not necessarily deep spending analysis or long-term financial planning. Likewise, someone who needs a broad collection of banking products may find a conventional bank or a more comprehensive financial platform more suitable.
It is also not the obvious choice for a person who sends money internationally only once every few years. In that case, a specialized remittance service may offer a more direct experience for the rare occasion, while a familiar bank may be simpler if the recipient and destination are already supported there. Común becomes more compelling when the need repeats often enough for convenience to accumulate.
How it compares with the usual alternatives
Compared with a traditional bank, Común appears more focused on the practical combination of payments, Latin America transfers, and card access. A bank may offer a wider financial relationship, but that breadth can also make a specific cross-border task feel less direct. I would choose the bank when I need established account management or broader services, and Común when its focused workflow better matches the transaction I am trying to complete.
Compared with a dedicated remittance app, Común has a broader everyday identity because the Visa debit card and person-to-person payments matter alongside international transfers. A specialist may still be preferable when your only concern is sending money abroad and you want a service built exclusively around that task. The better option depends on whether you value a single-purpose workflow or a more connected set of money activities.
Compared with a peer-to-peer payment wallet, Común’s Latin America focus gives it a clearer reason to exist for cross-border households. A general wallet may be more familiar among your local friends, so it could remain the easiest choice for splitting dinner or settling a small domestic expense. Común makes more sense when local payments are only one part of a larger pattern that includes international support and card spending.
The maintenance burden after the novelty fades
Financial apps do not demand maintenance in the same way as fitness or social apps, but they still require attention. You need to keep recipient information accurate, check transfer details, monitor card activity, and remember which balance or payment method you are using. The more roles Común takes on, the more important it becomes to keep your own routine organized.
My recommended setup would be deliberately simple. Use one clear purpose for the card, keep a note of recurring transfer recipients, and review the transaction before confirming it. This reduces the chance of sending money to the wrong person or losing track of why a payment was made. It also makes the app easier to audit at the end of the month.
There is a hidden advantage to this approach: it lets you judge the app by outcomes rather than by how polished the first session feels. After a few cycles, ask whether you are completing transfers with fewer steps, whether the card is genuinely used, and whether you are checking the app because it helps or because you are still trying to understand it. That is a more honest measure of long-term value than the excitement of opening a new financial product.
Small sources of friction to expect
Any app handling payments and transfers can feel slower than a casual social app because accuracy matters. Confirmation steps, identity checks, and security-related interruptions may be frustrating when you are in a hurry, but they are part of using a financial service responsibly. I would rather spend an extra moment reviewing a transaction than move too quickly and need to resolve a mistake later.
The card can introduce another layer of attention. You have to remember where it is accepted, keep track of its balance, and avoid assuming that having a card automatically makes the app a complete substitute for your bank. A useful personal rule is to keep enough backup access for essential purchases and travel, particularly while you are still learning how Común fits into your finances.
There is also a mental cost to having one more financial account. Even a well-designed app can add clutter if you already use several wallets, cards, and bank accounts. Before installing it, I would identify the exact problem it should solve. If the answer is vague, the service may become another icon you occasionally open without gaining much practical benefit.
What may cause fatigue over time
The biggest risk is not that Común lacks an appealing purpose; it is that the purpose may be too narrow for some users. If your international transfers are rare, the debit card does not replace an existing favorite, and local contacts use another payment method, you may stop opening the app after the first few weeks. That is a normal outcome, not a failure. Good tools still need a regular job.
Another possible source of fatigue is divided attention. When money is spread across multiple services, it becomes harder to remember where a balance sits or which card should be used for a particular purchase. Común can simplify a fragmented setup, but it can also add another layer if you adopt it without retiring or clearly limiting an older tool.
I would also avoid judging the app solely by whether it can perform a transfer. The more useful question is whether it improves the full routine around that transfer: preparing the payment, choosing the right recipient, confirming the details, and remembering what happened afterward. If the app helps only at the final tap but leaves the rest of the process confusing, its practical advantage may be smaller than expected.
For users who want extensive financial controls, sophisticated categories, or a broad suite of banking services, the focused nature of Común may eventually feel restrictive. In that situation, a full-service bank or a specialized financial management app could be the better long-term home, while Común remains a supplementary tool for cross-border payments.
My long-term verdict on Común
After looking beyond the first-week appeal, I see Común as a focused finance app with a credible chance of becoming a lasting tool for the right audience. Its strongest case is the combination of sending money to Latin America, paying people, and using a Visa debit card without forcing those needs into completely separate routines. That combination is specific enough to be useful and practical enough to support repeated use.
The app is less convincing as a universal replacement for a bank or every payment service you already use. People who rarely make international transfers, need advanced financial planning, or prefer to keep all banking under one established institution should think carefully before adding another account to their routine. The free price makes testing easier, but it does not remove the need to decide whether the app solves a recurring problem.
My advice is to start with one clearly defined workflow: a normal payment, a modest transfer to a known recipient, or a limited trial of the debit card. Pay attention to how much effort the entire process takes, not just how attractive the first session feels. If the app repeatedly saves you time and keeps cross-border money tasks in one place, it has earned a permanent spot. If it becomes a backup you never remember to use, uninstalling it may be the more honest choice.
Overall, I would recommend Común to people whose daily or monthly finances genuinely connect to Latin America and who appreciate having a card alongside payment tools. Its public reception, free access, and focused design make it worth trying, but its lasting value comes from repetition. Común earns its place through a dependable habit, not through novelty alone.
FAQ
What is Común: Your money, your way?
Común: Your money, your way is a personal finance app designed to help users manage everyday money more conveniently from a mobile device. After exploring its main features, the app appears focused on giving users a clearer view of their finances, organizing transactions, and making money-related tasks easier. Its usefulness will depend on the services available in your country and the account or financial products you choose to connect.
Is Común: Your money, your way safe to use?
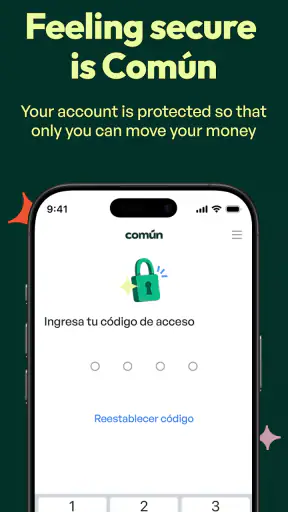
Financial applications require users to share sensitive information, so security should be considered before creating an account. Común may use standard protections such as account authentication, encrypted connections, and device-based security, but users should still review the app’s privacy policy and permissions carefully. Download it only from an official store, use a strong password, enable available security features, and avoid accessing your account on unsecured public networks.
Does Común charge fees for using its services?
The cost of using Común depends on the specific features, account type, transactions, and financial services available in your region. Some functions may be free, while others could involve subscription costs, transfer fees, card charges, withdrawal fees, or third-party expenses. Before depositing money or ordering any related product, check the current pricing information inside the app and read the applicable terms carefully.
Can I use Común if I live outside its supported country or region?
Común’s availability is likely limited by country, residency requirements, local regulations, and the financial services it supports. During registration, the app may request identification, a local address, or a compatible phone number. If you are traveling or living abroad, certain functions may not work as expected. Check the official store listing and Común’s eligibility requirements before downloading or attempting to open an account.
What should I do if I have a problem with my Común account or transaction?
If you experience a failed transfer, login issue, missing balance update, card problem, or suspicious activity, use Común’s official support options within the app or on its verified website. Keep transaction dates, reference numbers, screenshots, and relevant messages available when contacting support. Never share your password, verification codes, or full security details with anyone claiming to provide assistance through unofficial channels.


